Find the right guide
Start with the format overview, then use the industry report for market data or the monetization guide for creator economics.
Microdrama 101: Complete Guide to the $20B Vertical Drama Market · How Microdramas Make Money (2026): Coin IAP, Ads & Creator ROI
Microdrama stopped being a niche mobile format years ago. In 2026, it is a multibillion-dollar global category with its own platform leaders, its own shakeout, and its own production revolution happening in real time.
Here is the state of the industry, grounded in the numbers analysts and platforms have actually published this year.
Quick Stats: Microdrama in 2026
| Metric | Figure |
|---|---|
| Global in-app microdrama revenue (Deloitte forecast, 2026) | ~$7.8B, more than double 2025 |
| Global microdrama revenue, broader definition (Omdia estimate, 2026) | ~$14B, up from ~$11B in 2025 |
| China's domestic microdrama output (2025 actual) | ~100B yuan (~$14.6B), doubling year over year |
| China's projected 2026 output | >120B yuan (~$16.5B) |
| App-store category revenue, Q1 2024 vs Q1 2025 | $178M → ~$700M |
| Global microdrama app downloads, 2025 | 2.3B+, more than doubling year over year |
| ReelShort gross consumer spend, 2025 | ~$1.2B, 70M+ monthly active users |
| DramaBox revenue / net profit, 2024 | $323M / $10M |
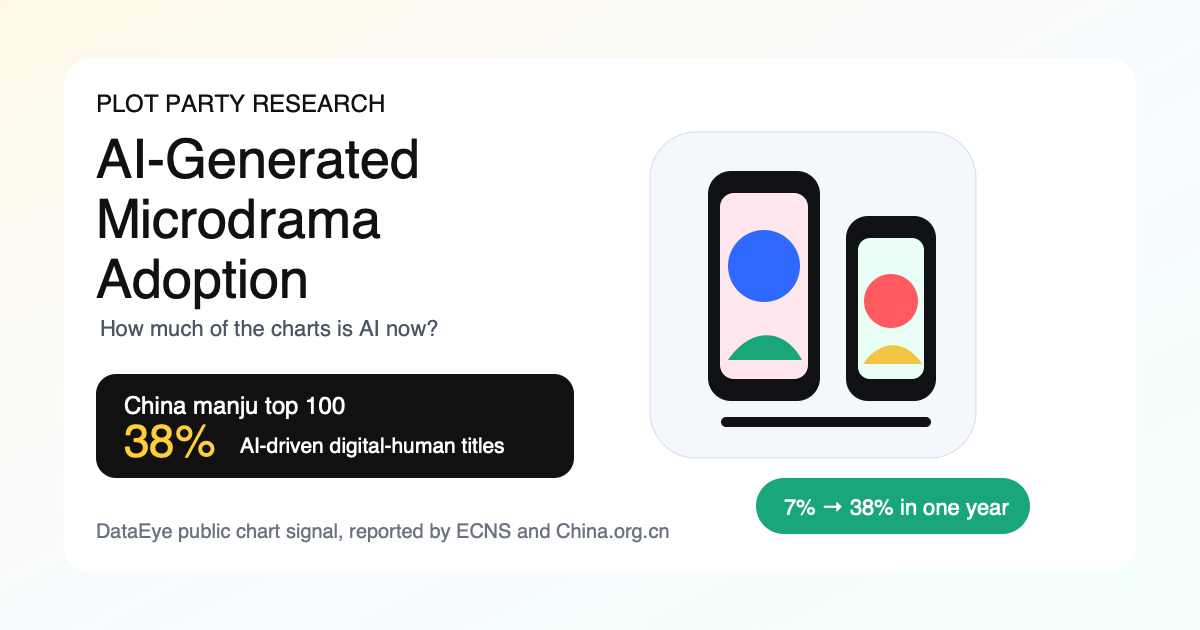
| Share of top-100 China chart titles that are AI-driven, Jan 2026 vs a year earlier | 38% vs 7% |
How Big Is the Market, Really?
Ask three analysts how big microdrama is and you will get three different numbers — because they are measuring different things.
Deloitte forecasts global in-app microdrama revenue (the money spent inside apps like ReelShort and DramaBox on coins and subscriptions) at roughly $7.8 billion in 2026, more than double what it projected for 2025. That is the narrowest, most conservative definition.
Omdia takes a broader view of the category and estimates global microdrama revenue at around $11 billion in 2025, climbing to about $14 billion in 2026.
China's domestic industry, tracked separately by local regulators and press, is the largest single piece of the puzzle. Chinese microdrama output reportedly hit roughly 100 billion yuan (about $14.6 billion) in 2025, doubling year over year, and is projected to exceed 120 billion yuan (about $16.5 billion) in 2026 — a figure that has already overtaken China's domestic theatrical box office.
The takeaway for creators and platforms is not which number is "correct." It is that every measure of this market points the same direction: fast, compounding growth, with app-store revenue for the category jumping from roughly $178 million in Q1 2024 to nearly $700 million in Q1 2025, and global downloads surpassing 2.3 billion in 2025.
Where the Growth Is Coming From
Microdrama's growth is not evenly spread. Four regional stories matter most in 2026.
United States — The largest single non-China market. The US generated the majority of ex-China microdrama revenue in 2024 and is expected to represent roughly half of all ex-China revenue by the end of 2026. It also drives the highest revenue per user for leading apps like ReelShort.
China — Still the epicenter, both commercially and technologically. It is the market where AI-native production is scaling fastest, and where local governments are funding production hubs and offering subsidies for microdrama studios.
Japan — A smaller but fast-maturing market, forecast to top $1.2 billion by 2030, helped by local payment integrations and growing native-language production.
Latin America — The surprise growth engine of 2026. Brazil has overtaken the US as the single largest source of ReelShort downloads, reflecting how well the ad-supported, price-sensitive model fits price-conscious mobile markets. Indonesia, Thailand, and the Philippines are following a similar pattern for challenger apps.
The Platform Landscape
A handful of platforms control most of the category's revenue, but the field is wider — and more competitive — than most outside observers assume.
| Platform | Parent / Studio | Standout 2025–2026 Data |
|---|---|---|
| ReelShort | Crazy Maple Studio (COL Group) | ~$1.2B gross consumer spend in 2025, 70M+ MAU; runs deliberately unprofitable to buy growth |
| DramaBox | Dianzhong Technology | $323M revenue, $10M net profit (2024) — the clearest profitable-at-scale platform; ~50M MAU; partnered with The Trade Desk in April 2026 for programmatic ad inventory |
| ShortMax | Jiaxing Jiuzhou Culture Media | 3,888% YoY revenue growth (2023–2024), the fastest of any major platform; 30M+ peak MAU across 200+ countries; also supplies content to TikTok's PineDrama |
| NetShort / GoodShort / DramaWave | Various (Xinyue Technology and others) | Fill out the top tier by revenue outside China |
| TikTok PineDrama | ByteDance | Launched in early 2026 as a dedicated serialized short-drama app, with ShortMax among its content partners |
| Character.AI | Character.AI | Entered with three AI-character microdrama titles in 2026, leaning on its existing engagement base |
Together, ReelShort and DramaBox have each passed $450 million in cumulative in-app revenue. New studio entrants keep arriving too — India's Yash Raj Films announced an approximately $18 million microdrama investment and a new platform in April 2026, becoming the first major Indian studio to enter the category.
Monetization: Coins Are Still King, but Ads Are Catching Up
Coin-based, pay-per-episode in-app purchases remain the dominant monetization model across nearly every major platform, giving studios granular control over which episodes unlock revenue.
But 2026 is the year ad-supported monetization went from "secondary option" to "strategic bet." DramaBox's programmatic ad partnership with The Trade Desk — the first of its kind for a vertical drama platform — opens a second, less friction-heavy revenue channel that does not depend on users pulling out a credit card. Expect more platforms to blend both models rather than pick one, especially in price-sensitive markets like Latin America and Southeast Asia. For a deeper breakdown of how these two models compare for creators, see our guide on how microdramas make money.
The Shakeout Has Already Started
Growth headlines hide a harder truth: this is a consolidating market, not an infinitely expanding one.
Analysts estimate that the top three platforms control roughly 60% of ex-China revenue, while a long tail of smaller apps competes for the rest. Many of those smaller apps are burning through venture funding with sub-$50,000 monthly revenue and no credible path to profitability — and estimates suggest as much as 70% of currently active microdrama apps could shut down or be absorbed within two years.
That matters for creators and IP holders deciding where to publish, license, or build a following. Platform selection is no longer just about audience size; it is about which platforms will still exist in 18 months.
The AI Production Shift
The other force reshaping the industry in 2026 is production itself. AI is compressing the traditional microdrama pipeline — companies are reporting workflows that used to take 11 manual production steps down to roughly 3, cutting total production time from about three months to as little as one, and reducing costs to a fraction of a traditional live-action shoot.
In China, the scale is striking: more than 50,000 AI-native titles reportedly went live on Douyin in a single month in early 2026, and studios are now allocating around 30% of production budgets to AI-driven workflows. The leading AI video models behind this shift — Seedance 2.0, Kling 3.0, and Vidu — have moved from experimental tools to core production infrastructure for entire studios.
We cover exactly how much of the chart this AI shift represents, and what "AI-generated" actually means in practice, in a dedicated deep dive: AI-Generated Microdrama Adoption: How Much of the Charts Is AI Now?
What This Means for Creators and IP Holders
Three things follow from this data:
The cost of trying an idea keeps falling. AI-assisted production means a small team can test a premise, a character, or a hook without committing to a full traditional budget. Our guide to creating an AI microdrama walks through that workflow end to end.
Distribution is consolidating, but content demand isn't shrinking. Fewer platforms will likely survive, but the ones that do — ReelShort, DramaBox, TikTok PineDrama, and a handful of challengers — need a constant supply of new premises, characters, and episodes to stay competitive.
Character consistency and localization are now competitive advantages, not afterthoughts. With ad-supported monetization and multi-market distribution both growing, the studios and creators who can keep a character consistent across episodes and languages will have an edge. See our comparison of the best AI character consistency tools in 2026 for how that workflow is evolving.
For IP holders sitting on unused characters, worlds, or franchises, this is also the moment the economics finally work: production costs have dropped enough that licensing a smaller IP into a microdrama series is no longer a rounding-error decision. Our guide for IP holders covers how that monetization path works in practice.
Outlook for the Rest of 2026
Expect three trends to keep compounding through the back half of the year:
- Ad-supported monetization spreads beyond DramaBox as more platforms chase price-sensitive markets in Latin America and Southeast Asia.
- AI production stops being a headline and becomes assumed infrastructure — the story shifts from "is this AI-made?" to "is this good?"
- Consolidation accelerates, with weaker apps folding or getting acquired while the top platforms and a few well-capitalized challengers (TikTok PineDrama, Character.AI, new studio entrants like Yash Raj Films) absorb their audiences.
The format is still young enough that the leaderboard will keep changing. But the underlying demand — short, emotionally direct, serialized stories built for a phone screen — is not a fad. It is a new default for how a huge slice of the world watches drama.
Ready to build for where this market is going? Start creating on Plot Party, or explore our Microdrama 101 guide if you're just getting started.
Sources
- Deloitte: Tiny episodes, massive appeal — short-form serials
- Yahoo Entertainment: Vertical micro-dramas are an $8 billion business
- StartupHub.ai: Microdramas explained — the $8 billion vertical drama boom
- The Next Web: China's $16.5B micro-drama industry and AI-generated video
- Sensor Tower: Short-drama redefines mobile entertainment and challenges games
- Filmustage: Short drama apps compared — ReelShort vs DramaBox in 2026
- Vitrina: Micro drama distribution platforms 2026
FAQ
How big is the microdrama industry in 2026?
Estimates vary by methodology. Deloitte forecasts about $7.8 billion in global in-app microdrama revenue for 2026, Omdia estimates a broader $14 billion global figure, and China's domestic industry alone is projected to exceed 120 billion yuan (about $16.5 billion). All three point to rapid, compounding growth.
Who are the biggest microdrama platforms in 2026?
ReelShort and DramaBox lead by revenue, each having passed $450 million in cumulative in-app revenue. ShortMax is the fastest-growing challenger, and TikTok's PineDrama and Character.AI are notable new entrants competing for the same audience.
Is the microdrama market oversaturated?
The top of the market is consolidating rather than saturating — the top three platforms control roughly 60% of ex-China revenue, and analysts expect a large share of smaller, underfunded apps to shut down or get absorbed within two years. Demand for new content and IP is still growing even as weaker distributors exit.
How much of microdrama production now uses AI?
It depends on the category. In China's AI-heavy digital-human and animated chart segment, AI-driven titles reportedly made up 38% of the top 100 in January 2026, up from 7% a year earlier. Across the wider industry, AI is used unevenly but is increasingly embedded in scripting, previsualization, localization, and ad creative even when the final episode looks conventional. See our dedicated adoption breakdown for the full picture.
Run Top AI Video & Image Models in Plot Party Studio
- Seedance 2.5 — Multi-reference AI video generation
- MiniMax H3 (Hailuo 03) — Reference-to-video and dialogue workflows
- SeedVR 2 — AI video upscaling and detail restoration
- Nano Banana 2 — Image generation and reference consistency
- GPT Image 2.5 — Image editing and character sheets
- Midjourney — Cinematic key art and world building